
Compliance
CFPB and Reg B
Adverse decisions need explanations. Session-level evidence of what the model saw, did, and decided.
At a glance
Who this covers, and who enforces it
Creditors — including AI-based underwriting and pricing systems — whose decisions must meet ECOA’s anti-discrimination and adverse-action-notice requirements.
- Instrument
- ECOA + Regulation B (12 CFR 1002)
- Enforced by
- CFPB, with DOJ and state enforcement
- Since
- 1974 — applies fully to AI-made credit decisions
- Key duty
- Specific, accurate adverse-action reasons
- Deadline
- Notice within 30 days of adverse action
Requirements
What it asks for
- 1Specific, accurate reasons for adverse action
- 2No proxy discrimination in model outputs
- 3Documentation of decision logic
- 4Records ready to answer a complaint or exam
Evidence mapping
What PRISM records against each requirement
Every plan records this evidence as your AI runs. Compliance Reports, which turn it into a reviewed, framework-mapped report, are delivered as a service, on request.
- Adverse action reasons
- Traces capture the exact input and model output behind every decision.
- Proxy discrimination testing
- Synthetic Scenarios and Evaluators test for disparate outcomes before and after a change.
- Decision logic documentation
- AI Remediation records why a model changed and what was validated.
- Complaint-ready records
- Sessions reconstruct the full user-facing conversation on request.
Primary source
Read the actual text
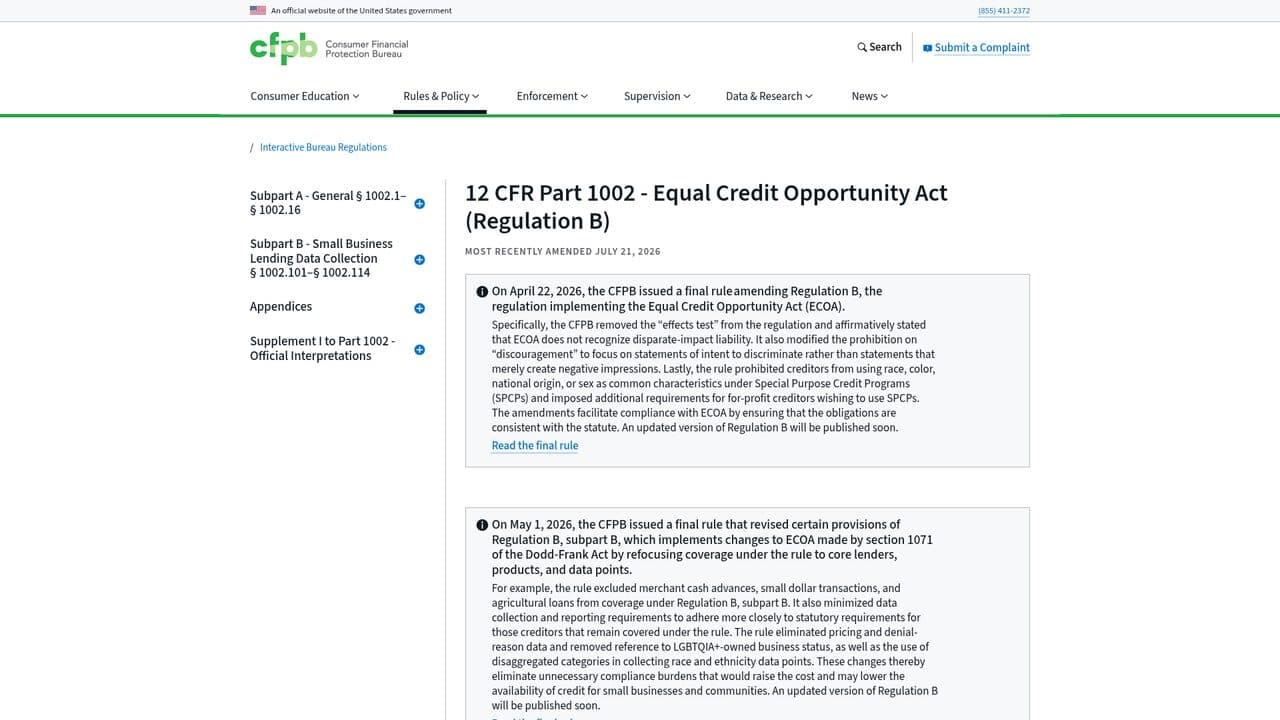
Everything on this page is drawn from CFPB — 12 CFR Part 1002, Regulation B (ECOA). The capture is live, not a paraphrase — go straight to the source and check us.
Evidence, not certification
This page describes CFPB and Reg B’s publicly available requirements and how PRISM’s evidence layer supports them. It is not legal advice, and it does not constitute certification, regulatory approval, or a guarantee of compliance. CFPB and Reg B compliance remains your organization’s responsibility, in consultation with qualified counsel.
Ask us about your framework
Tell us how CFPB and Reg B applies to your systems and we'll show you the evidence path.